

Welcome to another week! For the new readers: every week I comment on the top prediction markets—selected by volume, volatility and surprising resolutions—across (geo)politics, elections, macro, tech and science. Markets first, news through their lens, not the other way around.
Let’s see what changed in the world!
Weekly Outlook
US Inc.
Midterms
No week is a bad week if you are a Democrat. Blue sweep now has a 67% chance, up 4 points in a week. Republican Senate chances are the culprit, currently at the lowest level in a month:
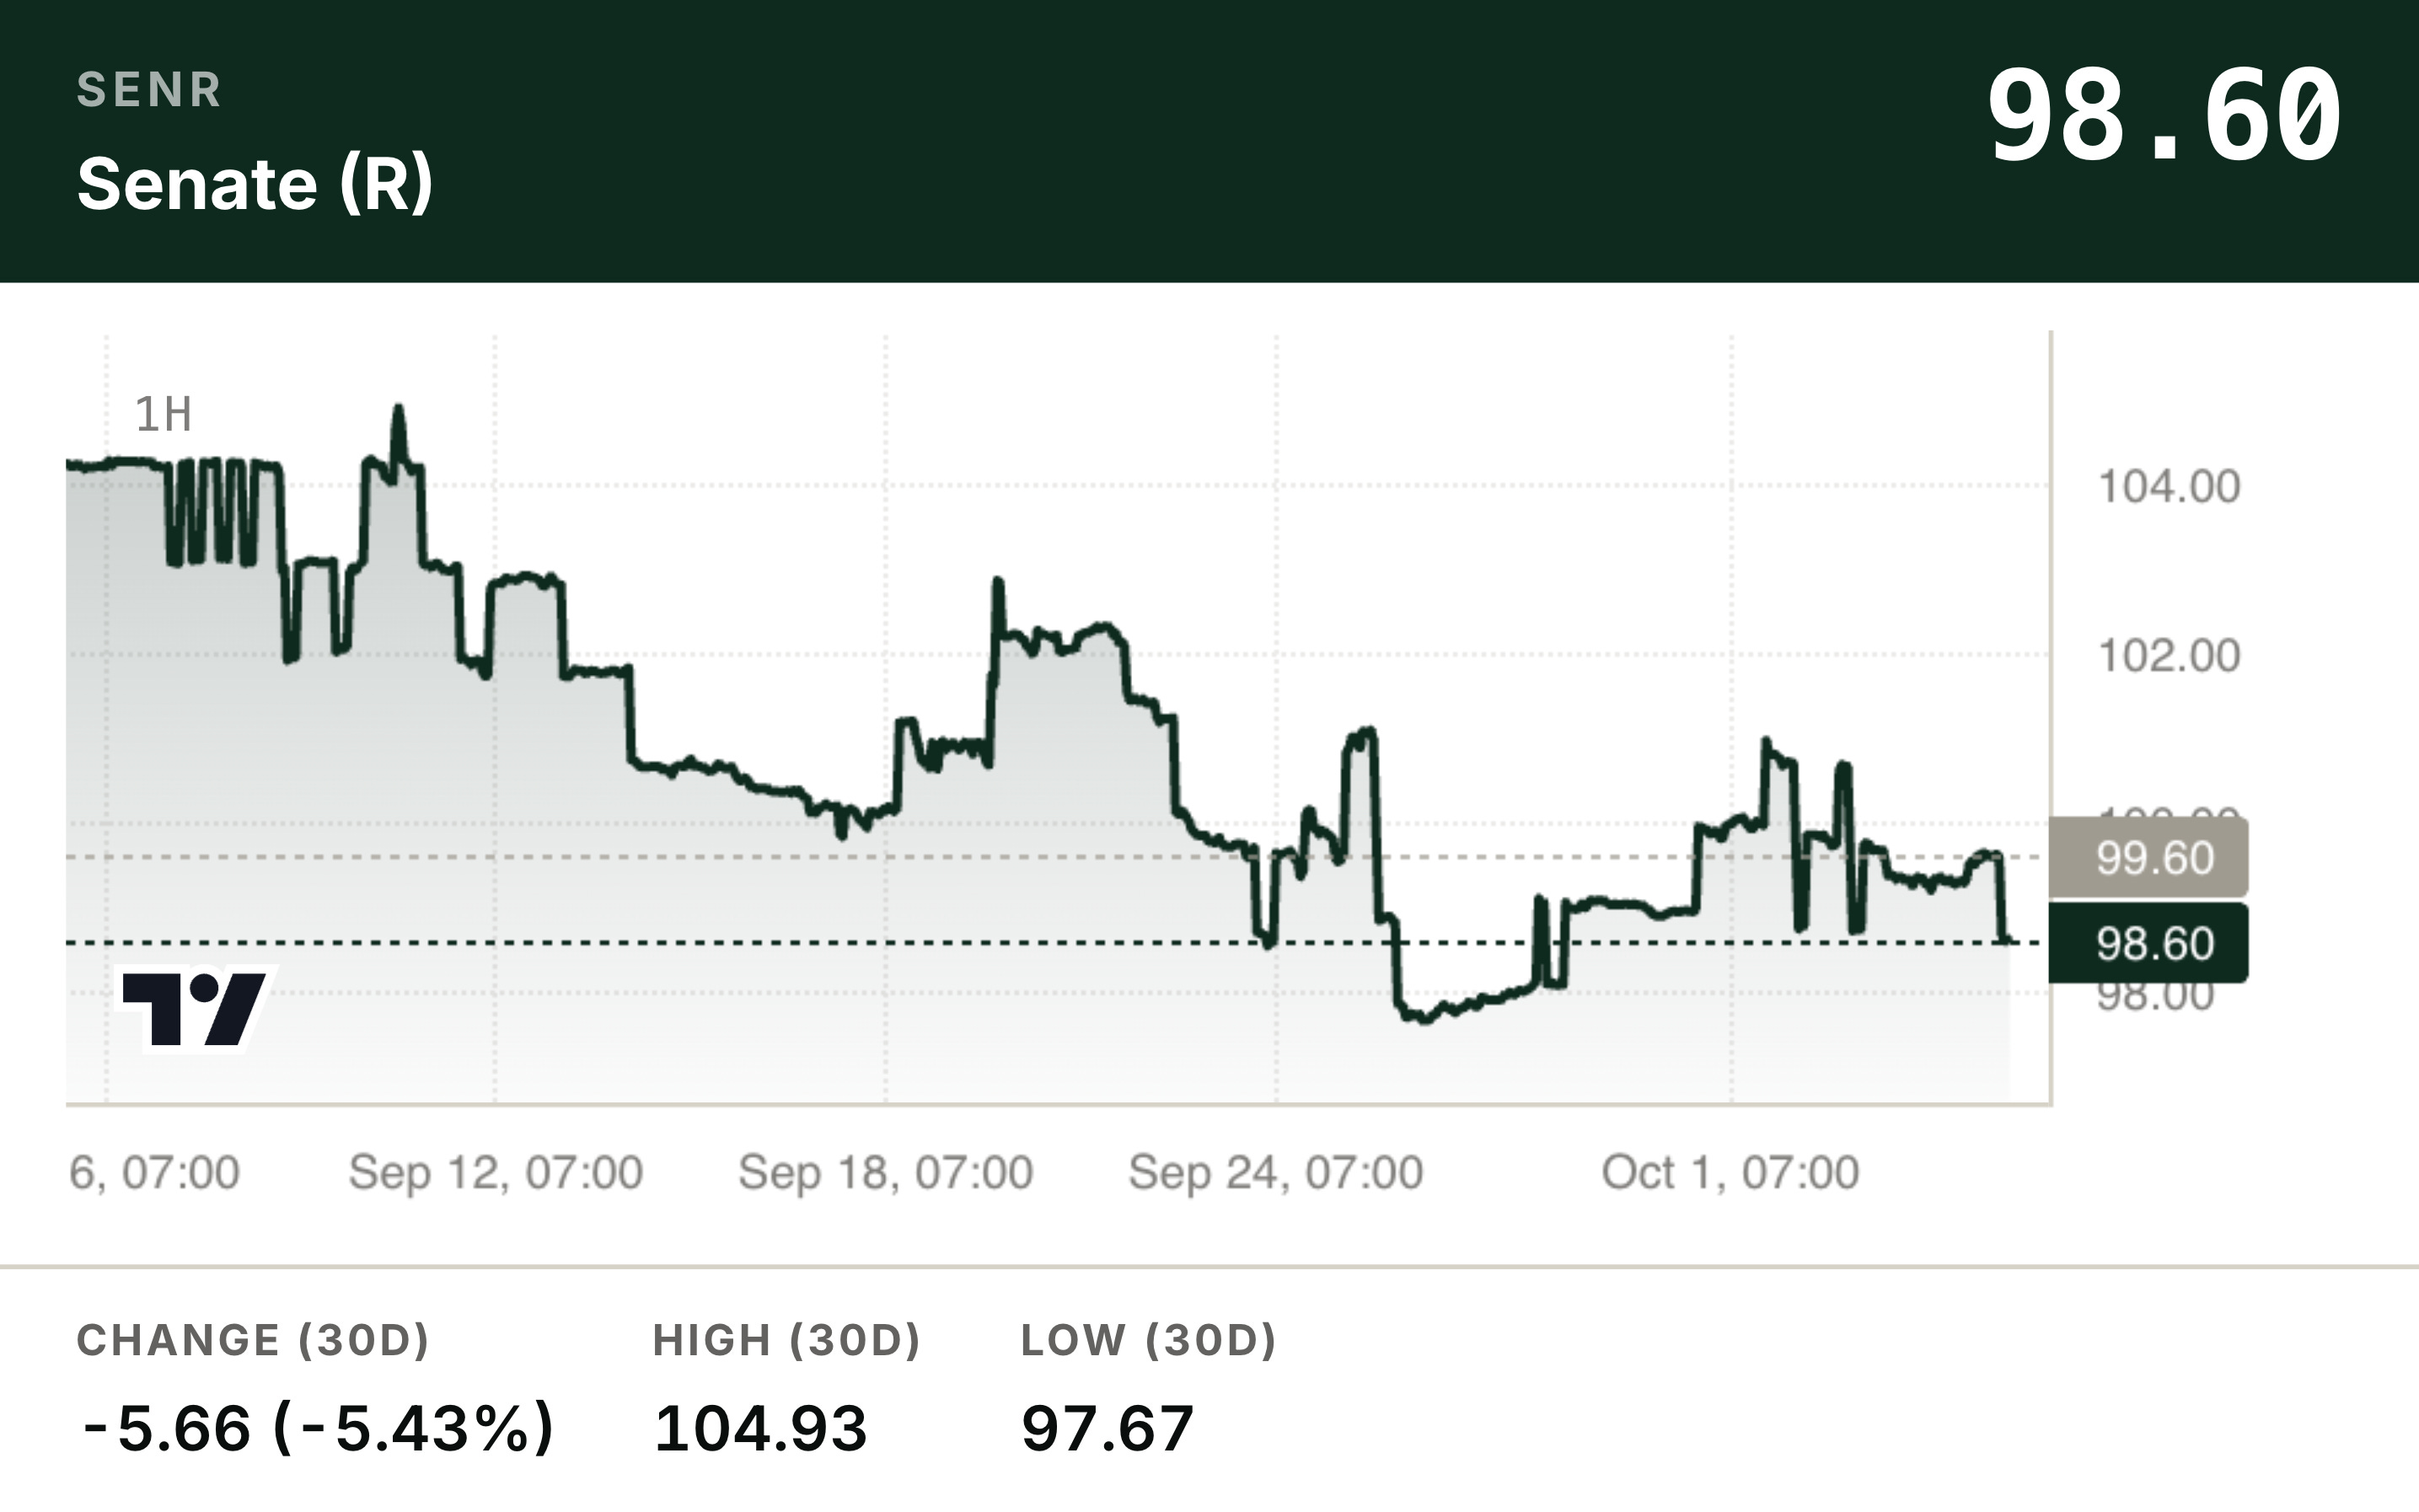
Last week was especially brutal for Republicans in Alaska, Ohio, Texas and Kansas. Even a 3-to-1 funding advantage in Texas is not enough to move the needle.
I’ll be launching my midterms forecast in the coming days and I’ll pit it against the market daily.
The Fed
Republicans at least got a break from the Fed. Officials could have announced another hike instead of calming markets about the rate path. A few of them presented dovish views on the short-term outlook, pushing the no-change odds in October to 84%.
That didn’t, however, stop the rising long-term yields. 30Y breached 5.50% last week and is close to breaching 5.65%:
The 10Y is just below 5.3%:
And whether he likes it or not, Trump is not going to be saved by a hold.
The Americas
Brazil Presidential Election
Brazil is fresh out of the first round of the presidential election. In a (not so) surprising outcome, Flávio Bolsonaro won the first round and is an 83% favorite to win the runoff.
My forecast saw this coming. Yesterday I published that the first round was close to 50/50, with Bolsonaro a 72% favorite overall. The model also called 3rd place correctly:
I’ll have a short update to the forecast before the second round. You can take a look at what assumptions drove my model in yesterday’s deep dive:
My Positions on Brazil Presidential Election

It’s been a while since I did an election deep dive. And by coincidence, it was Portugal! Now I venture again into the Portuguese-speaking world to point out where the market is wrong. And this time, I’m doing it properly.
Asia
No interesting markets in Asia last week.
Middle East & Africa
The Iran War
The Iran war is still in a stalemate. Negotiations have stalled since America sent its counterproposal to Iran on the eve of October. The deal market is flat, a decent sign given theta decay.
US officials and military met at Camp David on October 2 to discuss the current wars. Supposedly, a lot was decided, or deeply discussed. The White House continues its narrative about the war ending very soon, just after the midterms. The blockade and Strait of Hormuz opening markets are flat, though. Traders aren’t buying the rhetoric yet:
No kinetic action is expected in the foreseeable future:
On the commodities side, no diesel export ban is expected anymore:
European nations agreed to release their strategic reserves, calming the market for the time being.
The Houthis
The Houthis and Saudi Arabia continue to exchange strikes as the Yemen civil war reignites. Saudi-backed forces announced a plan to eliminate the Houthis, moving from preparations to action.
As a result, the oil infrastructure in the region is strained even further. The East-West pipeline is still not confirmed to be running, with traders slowly losing hope:
Luckily, the US-led escort operation in Hormuz is partially offsetting that.
Israel
To close out the Middle East, we have a potential flippening in Israel. Likud is leading in recent polls, making it increasingly likely that Netanyahu keeps his job:
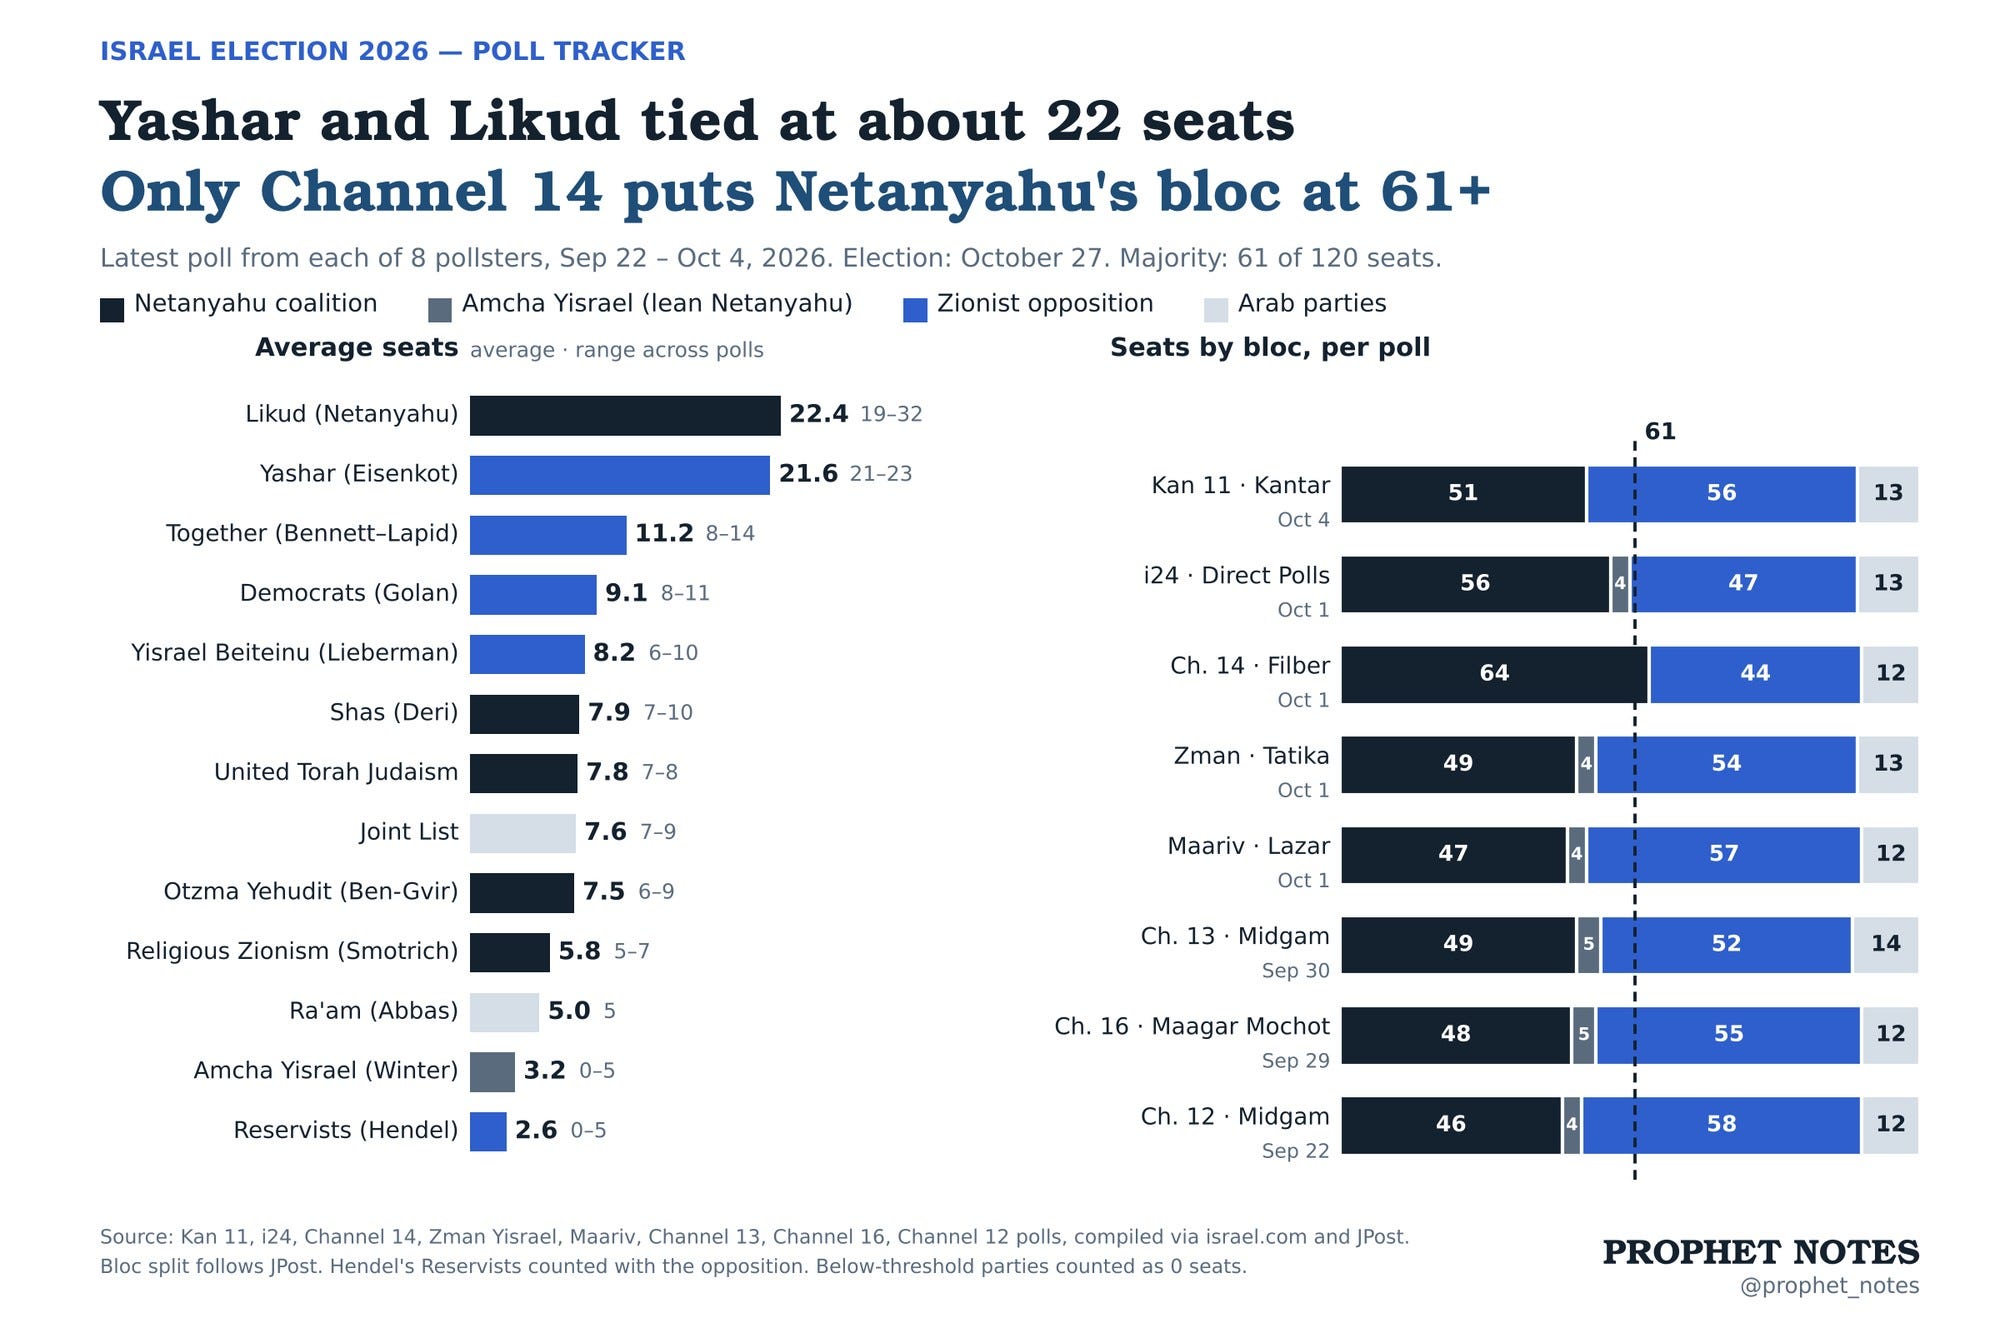
Traders now give Likud a 54% chance to win the election:
However, Eisenkot is still the favorite to be the next prime minister:
Looks like there are plenty more surprises ahead of us in this election.
Europe
The Ukraine War
The noise around a potential Russia-NATO escalation has quieted down:
The market fell as the narrative faded. However, the war is far from done. Russia is intensifying its energy strikes ahead of winter, and so is Ukraine. Russia also targets major Ukrainian cities to increase war fatigue.
The White House is still trying to arrange peace talks, with the newest push aiming to set up technical-level talks by the end of October. The market’s opinion on their potential success is clear:
Spain
Fresh news from the European morning—Spain’s PM called a snap election for November 29 after a major housing bill failed to pass parliament. The right-wing bloc is widely expected to win and form a coalition (PP+Vox):
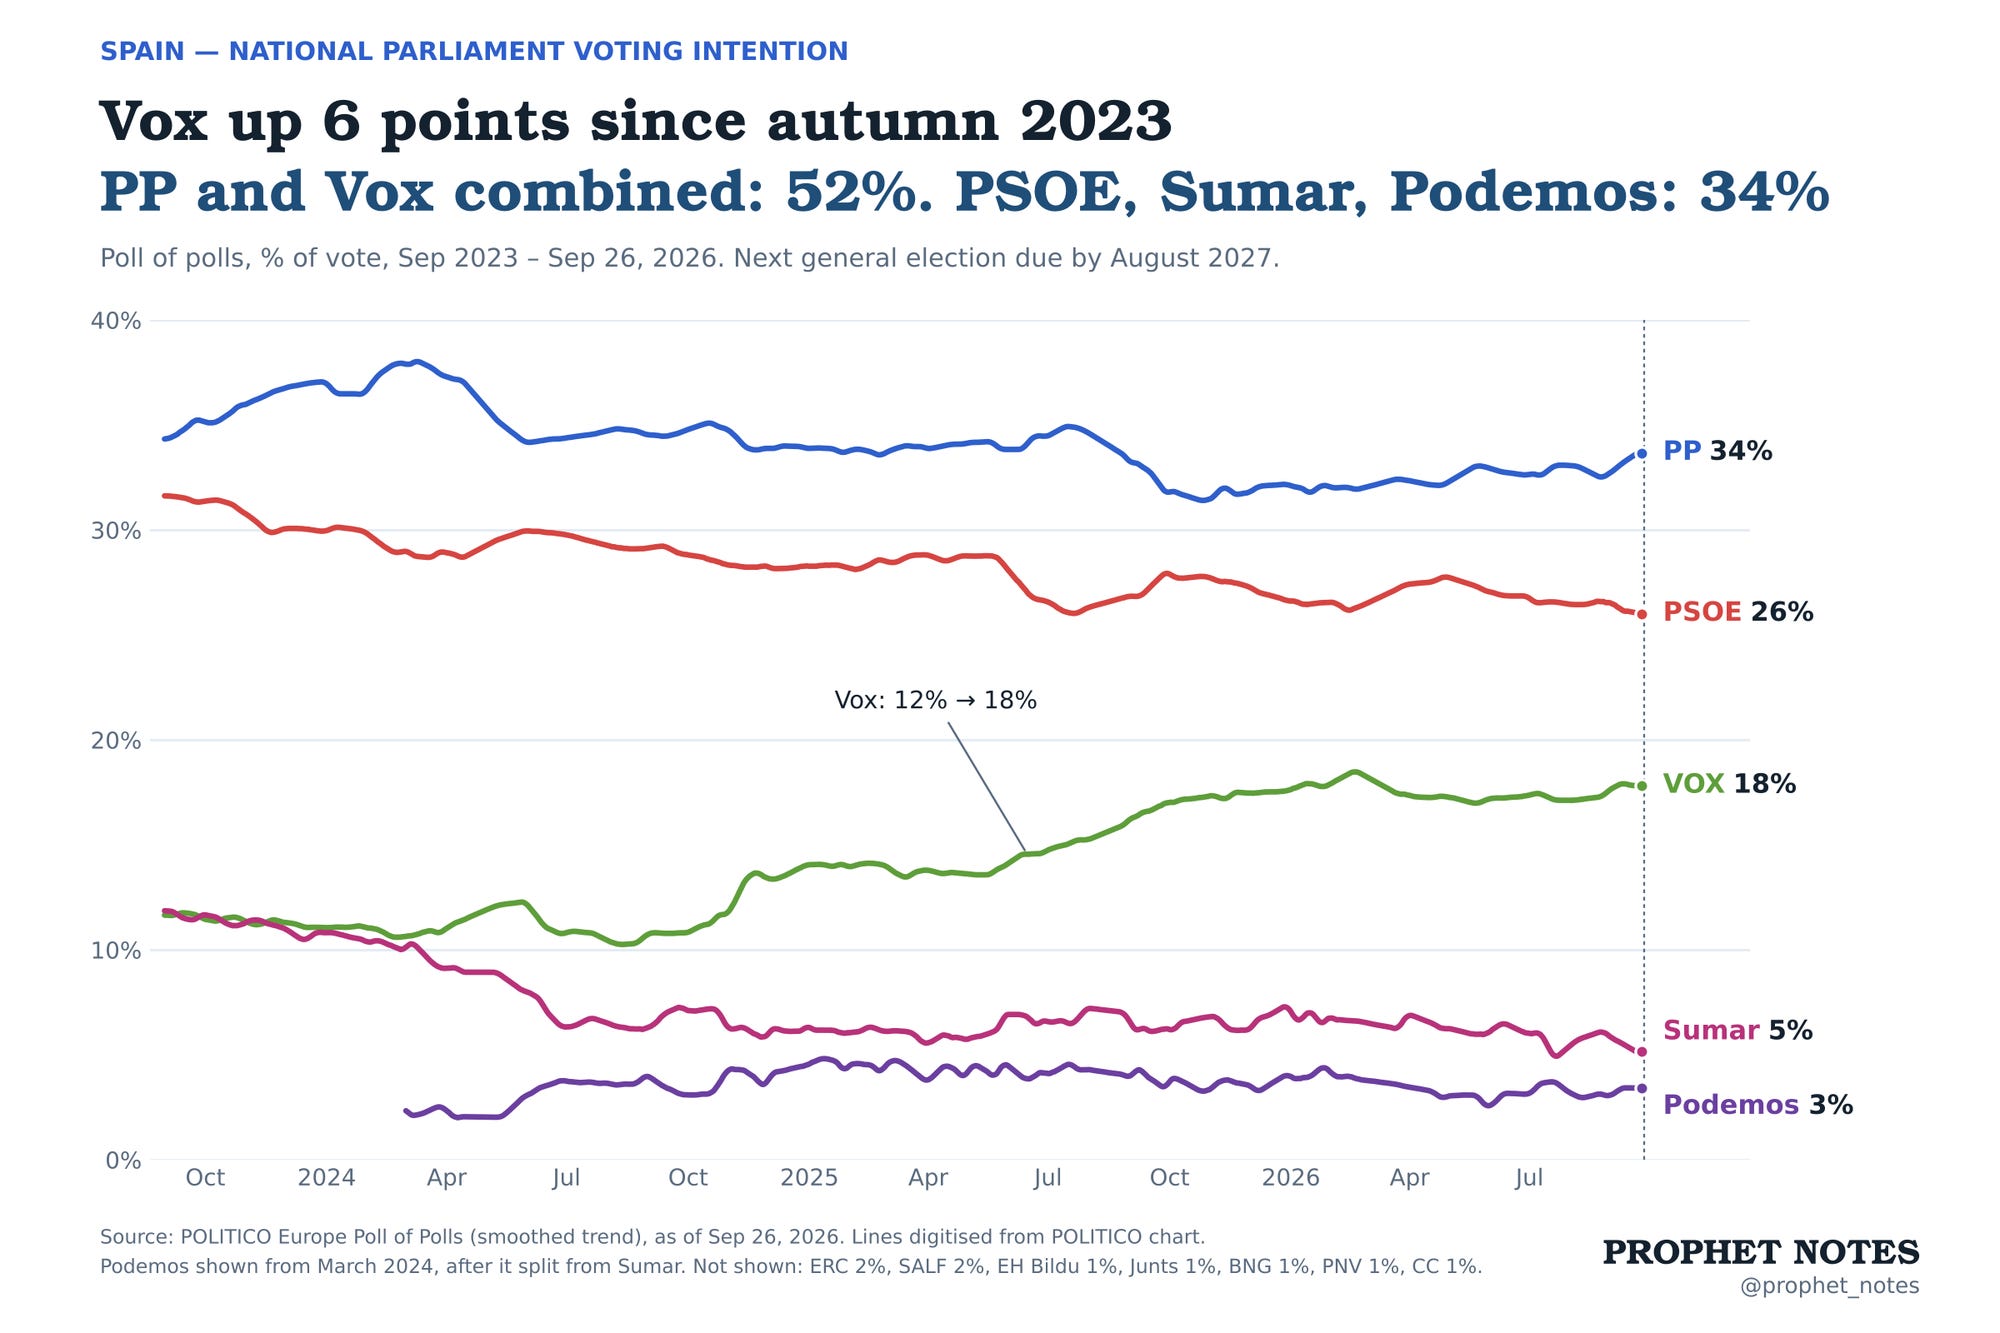
It will be an interesting one to model!
France
In France, Le Pen’s chances to be the next president rose by 6 points amid countrywide protests, which started as demonstrations against the state of the schooling system before turning violent.
Over 400 schools are closed due to deteriorating security conditions and over 5,000 people were arrested. Another protest push is planned for Tuesday.
Other
AI
Google rose from the ashes to once again dominate the benchmarks. Their newest model, Gemini 4 Argon, currently tops the text benchmark, ahead of Opus 5.5 and Fable 5.1.
Traders still expect Fable 5.5 to drop soon and leave Gemini far behind.
Wrap up
That’s all for today! Coming up: a Brazil update (as part of a wider forecast update on Ukraine and Iran) + a new midterms series; I’m also overdue for the State of PROPHET NOTES. Then I’ll focus on the Spanish election.
Stay strong and see you soon!
This is not official investment or life advice. Do your own research. These are only my opinions and I encourage anyone to do their own research before putting any money anywhere.